Why Are More Miami Homebuyers Considering Adjustable-Rate Mortgages?
Buying a property in Miami is one of the most important financial decisions for families and investors looking to build a future or expand their real estate portfolios. However, when mortgage interest rates remain elevated, many buyers explore financing alternatives that could help them manage monthly payments without compromising financial stability.
One option attracting renewed attention is the adjustable-rate mortgage (ARM), a financing solution that may offer certain advantages depending on a buyer's financial goals and long-term plans.
But how do these mortgages work, and when might they be worth considering?
What Is an ARM Mortgage, and Why Are Buyers Exploring It?
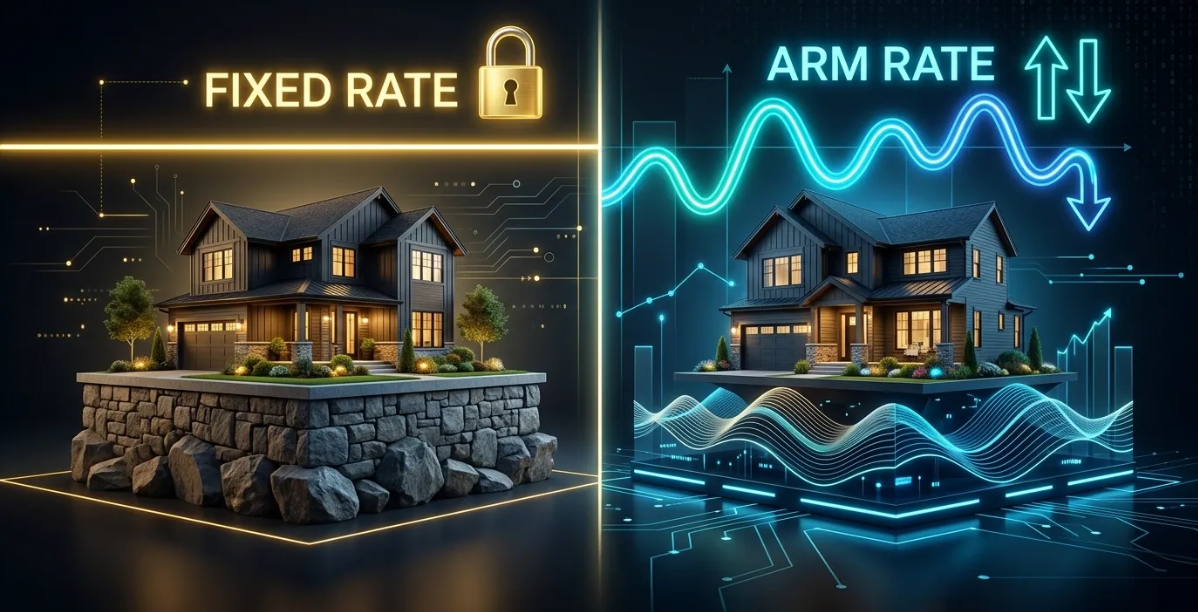
Unlike a fixed-rate mortgage, where the interest rate remains unchanged throughout the loan term, an adjustable-rate mortgage offers an initial fixed-interest period. Once that period ends, the interest rate may increase or decrease based on market conditions and the terms of the loan.
One of its main advantages is the chance to secure a lower initial interest rate, which may translate into more manageable monthly payments during the early years of homeownership.
This can be particularly appealing to buyers who want greater flexibility in their budgets or have a clearly defined real estate strategy.
For example, someone planning to sell a property within a few years may consider an ARM as part of their financing approach. It may also be worth exploring for buyers who want to compare different mortgage structures before committing to a traditional fixed-rate loan.
However, a lower initial interest rate does not necessarily mean lower borrowing costs over the life of the loan.
Once the initial fixed period ends, the interest rate and monthly payment may change. Before deciding, understand the adjustment limits, loan terms, and potential payment increases.
Buyers should also avoid assuming they can automatically refinance before the first rate adjustment, as refinancing depends on future market conditions, property value, financial qualifications, and lender approval.
 Smart Homebuying in Miami Goes Beyond Mortgage Rates
One of the most important recommendations I share with my clients is that the right mortgage is not necessarily the one with the lowest initial monthly payment, but the one that best supports their financial goals and future plans.
Before choosing a financing option, buyers should compare proposals from different mortgage lenders, considering not only the interest rate but also the APR, closing costs, lender fees, and overall loan terms.
Additional strategies may also help buyers improve their purchasing terms, including negotiating Seller Contributions, which may allow sellers to contribute toward eligible closing costs or mortgage rate buydowns, subject to loan guidelines.
In markets such as Miami Beach, Brickell, Downtown Miami, Coral Gables, North Miami, and Hollywood, properties vary significantly in their characteristics, ownership expenses, and investment potential. Understanding these differences is essential to making an informed real estate decision.
As a Miami Real Estate Broker Associate, my role goes far beyond helping clients find the right property. I guide clients through the buying process, evaluate opportunities, negotiate favorable terms, and collaborate with mortgage professionals so they can make confident, well-informed decisions.
Buying smart isn't simply about finding the best price. It is about creating a purchasing strategy that supports both your present needs and your future goals.
Thinking About Buying a Property in Miami?
Understanding your financing options can help uncover opportunities you may not have previously considered. An ARM mortgage may be worth exploring, but the right decision always depends on your individual circumstances and financial strategy.
My commitment is to guide you through the process, protect your interests, and help you make informed real estate decisions.
Categories
Recent Posts
GET MORE INFORMATION